Foreclosure Basics
What Are My Options If I'm Behind on My Mortgage in Texas?
Falling behind on your mortgage doesn't mean you're out of options — even in Texas, where the foreclosure process moves faster than in most states.
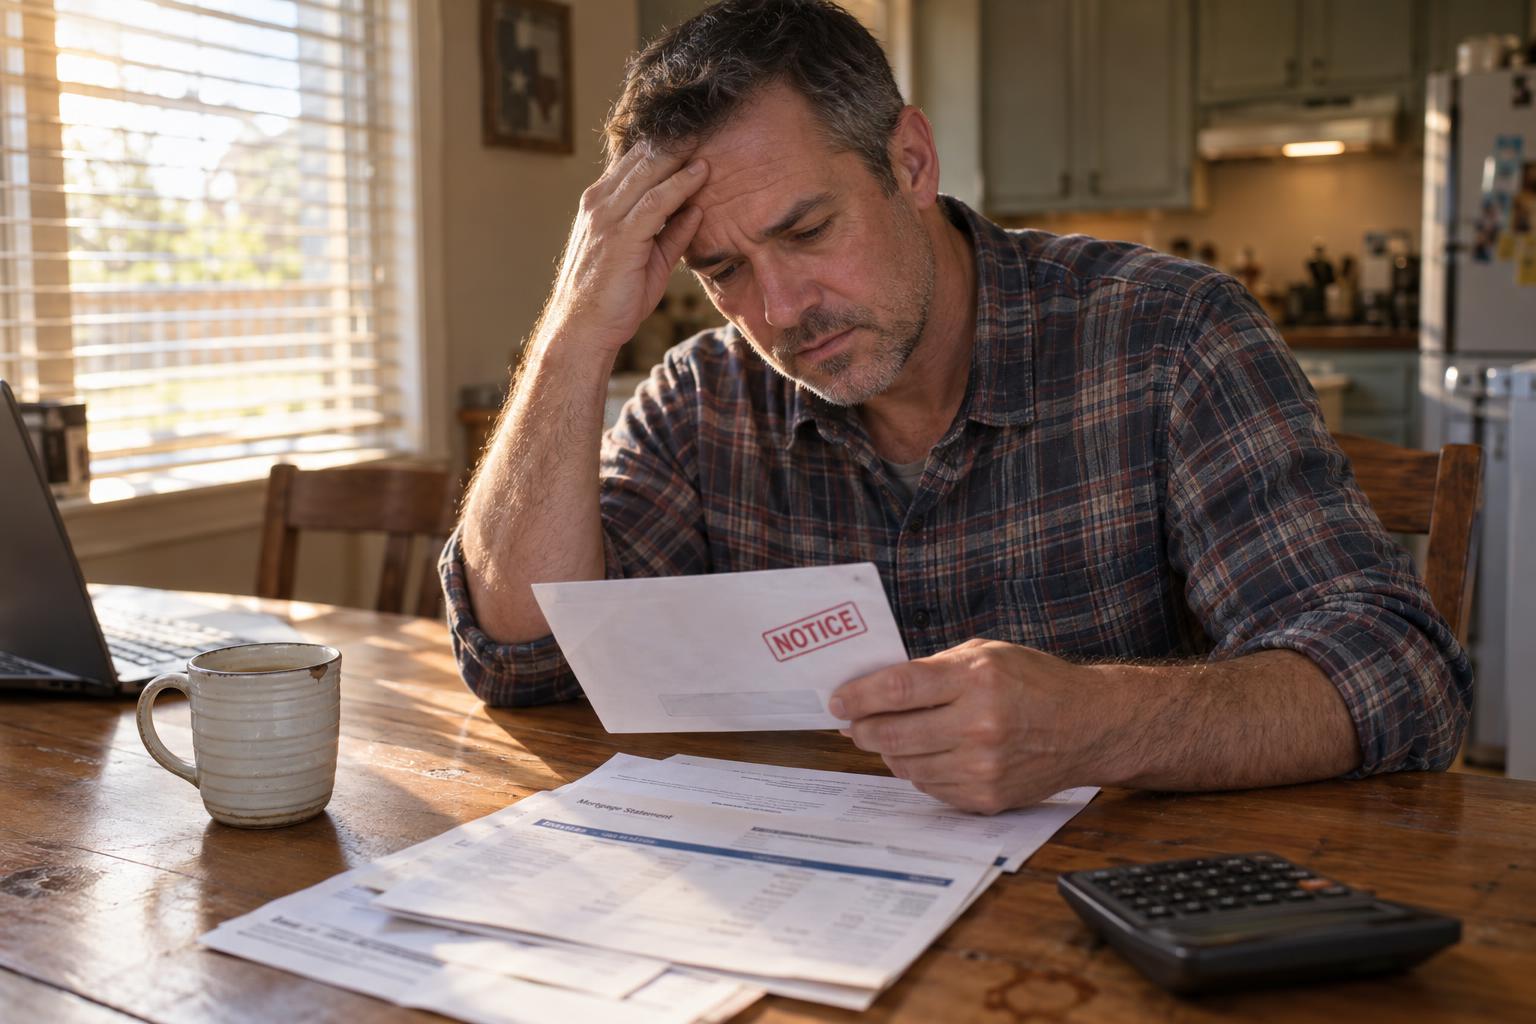
Falling behind on your mortgage doesn't mean you're out of options — even in Texas, where the foreclosure process moves faster than in most states. If you've missed a payment (or you can already see one coming), the worst thing you can do is nothing. The best thing you can do is find out, in plain language, exactly what's available to you before a lender's timeline starts making decisions for you.
Here's an honest look at where Texas homeowners typically stand, and what to do next.
You Have More Time Than You Think — But Not Unlimited Time
Texas is a non-judicial foreclosure state, meaning your lender doesn't need a court order to foreclose, which is a big reason the process here can move from a formal Notice of Default to a foreclosure sale in as little as 41 days. That sounds alarming, and it should get your attention — but it also means every week matters. Homeowners who reach out for help early almost always have more options than those who wait until the sale date is already set.
Your Real Options When You're Behind on Payments
1. Loan modification. Your lender may be able to restructure your loan — adjusting the interest rate, extending the term, or rolling missed payments into the balance — to make your monthly payment manageable again.
2. Forbearance. A temporary pause or reduction in payments, usually for 3–6 months, if your hardship is short-term (job loss, medical event, reduced hours).
3. Repayment plan. Your lender adds a portion of your past-due amount to each future payment until you're caught up.
4. Reinstatement. If you can come into money — a tax refund, insurance payout, help from family — paying the full past-due amount in one lump sum immediately stops the foreclosure process.
5. Selling the home — traditional or short sale. If keeping the home isn't realistic anymore, selling before foreclosure protects your credit far more than letting the process run its course.
6. Deed in lieu of foreclosure. You voluntarily transfer the property back to the lender in exchange for being released from the mortgage debt.
7. Doing nothing. This is technically an "option" — but it's the one that costs you the most: it maximizes credit damage and removes your ability to control the outcome.
Why the Right Choice Depends on You, Not a Checklist
No blog post can tell you which option fits your situation. That depends on things only you know: how much equity you have, whether your hardship is temporary or long-term, and whether you want to keep the home or you're ready to move on.
What To Do Right Now
Don't ignore letters or calls from your servicer. Gather your mortgage statement and a rough sense of your income and expenses. And talk to someone who isn't trying to sell you something you don't need — a free, no-pressure conversation is the fastest way to know exactly where you stand.
Let's Figure Out What Fits Your Situation
Every homeowner's path out of this is different, and the fastest way to find yours is a real conversation. I've been in this exact situation myself, which is part of why I built the Good Deeds Program — a free, no-obligation resource for Central and South Texas homeowners. No call center, no pressure, just a straightforward look at what's realistic for keeping your home, selling it, or negotiating with your lender.